

Split Pay: Split Bills in Two
Split Pay
- 4.8
- 445.00 Reviews
- 100.00K
- Downloads
- Free
- Price
Screenshots
Split Pay: Split Bills in Two Pros and Cons
Pros
- Splits bills quickly without requiring complex setup.
- Useful for shared meals, trips, rent, and everyday expenses.
- Clear payment tracking helps reduce confusion between participants.
- Supports fairer cost sharing when people owe different amounts.
- Simple interface makes it approachable for occasional users.
Cons
- All participants may need the app for the smoothest experience.
- Payment features and availability can vary by country or region.
- Users may need to verify entries carefully before confirming a split.
- Reliance on internet access can limit use while traveling.
- Some advanced options may require in-app purchases or subscriptions.
 Analysis by All-app
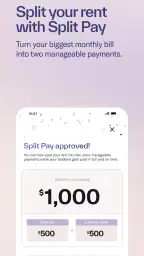
Splitting a large payment into two smaller payments sounds simple, but the practical value depends on whether it fits the way you already manage money. I spent time looking at Split Pay as a finance app rather than treating its short store description as the whole story. Its focus is clear: rent, mortgage, and car payments, with the aim of dividing one major obligation into two parts. That makes the app immediately interesting for people whose income arrives twice during a pay cycle.
The first impression is easy to understand. Instead of facing one large payment on a single date, you can think in two smaller stages. That can make a fixed expense feel less intimidating, especially when the rest of your budget is already organized around two paydays. The important question, though, is whether this remains useful after the initial relief wears off. In my view, the answer depends less on novelty and more on whether you are willing to keep the routine accurate every month.
What the first week feels like
The appeal is strongest when a household has a predictable income pattern but a payment schedule that does not match it. Imagine being paid near the beginning and middle of the month while your rent is due around one of those dates. Without a plan, the first payday can disappear into housing costs, leaving the rest of the month uncomfortably tight. Splitting the obligation into two planned portions gives each payday a job, which is often easier to follow than trying to protect the entire amount at once.
I also like the psychological side of this approach. A smaller planned contribution can feel more manageable than watching a full rent or mortgage amount leave the account. That does not reduce the total cost, of course, but it can improve the way the expense fits into a personal budget. For someone who regularly says, “I can afford this monthly, but not all at once,” the concept is much more practical than a generic expense tracker that merely records the problem afterward.
There is a useful distinction between planning and borrowing here. The app’s central idea is best understood as payment organization, not a magic reduction in what you owe. You still need enough money across the month to cover the complete obligation. I would therefore recommend starting with a written budget beside the app during the first cycle. Mark the two intended contributions, then check whether groceries, transport, utilities, and other automatic charges still fit around them.
A realistic example is a renter who receives income twice a month and normally spends the first payday almost entirely on housing. With a split-payment routine, that person can reserve one portion from the first deposit and another from the second. The benefit is not just smaller-looking numbers; it is a clearer cash-flow plan. The trade-off is that the plan only works if both portions are actually protected instead of being spent because the balance temporarily looks available.
That last point is easy to underestimate. A banking balance can create false confidence when money earmarked for a later payment remains in the account. I would treat each portion as already spent, even before the final payment is made. If you use the app while also keeping a separate note or calendar reminder, the system becomes more dependable. Relying on memory alone is where the convenience can quickly turn into stress.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
The application comes from Split Pay and is listed as a free finance app for everyone. It has reached over one hundred thousand installs and holds a 4.8 average from around three thousand ratings, with hundreds of written reviews. Those figures suggest that the basic idea is connecting with a meaningful audience, but popularity should not be confused with suitability. Someone looking for detailed household accounting may still find a full budgeting service more appropriate.
Who gets the quickest benefit
The strongest match is a person with recurring, predictable housing or vehicle costs and income that arrives in two regular stages. It can also help couples who want a simple shared rhythm: each person sets aside a portion, then the full payment is handled according to their existing arrangement. The app is less compelling for someone with irregular freelance income, constantly changing bills, or no reliable way to reserve money between payment dates.
It may also be useful for people who understand their budget but struggle with timing. Traditional spreadsheets and banking tools can show totals very well, yet they often leave the user to decide when money should be moved aside. A split-payment approach adds a behavioral rule: do not wait until the due date to find the full amount. That rule is the real value, and the interface matters mainly because it helps turn the rule into a repeatable habit.
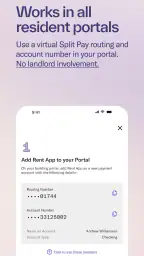
I would not recommend using it as a substitute for checking the actual terms of a lender, landlord, or service provider. Dividing money in your own plan does not automatically mean the recipient accepts two separate transactions. Before changing how you pay, confirm whether the payment must arrive in one transaction or by one deadline. This is one of the most important practical checks because a budgeting plan and a creditor’s payment policy are not the same thing.
Why the value can last beyond the novelty
After the first month, the app has to earn its place by reducing repeated mental work. The strongest long-term use is not opening it for entertainment or constantly adjusting the same plan. It is establishing a routine around each recurring obligation, then checking that the two-part schedule still matches your income and due dates. If it helps you make that decision quickly, it can remain useful even after the original excitement disappears.
For rent, the recurring nature makes the idea easy to understand. Mortgage payments can benefit from the same cash-flow discipline, although the larger amount makes accuracy even more important. Car payments are another natural fit, particularly for someone who wants to reserve money gradually rather than wait for one large withdrawal. In all three cases, the app’s usefulness comes from repetition: the same type of expense returns, and the same preparation can be applied again.
One non-obvious advantage is that splitting a payment can expose whether your payday schedule is actually compatible with your obligations. If the second portion always arrives too close to the due date, the problem is not simply a lack of discipline. It may mean the plan needs an earlier reserve, a different account, or a revised due-date arrangement. Used thoughtfully, the app becomes a way to test the timing of your budget rather than merely divide a number.
Another useful habit is to review the plan after any income change, not just when the payment itself changes. A new pay schedule, reduced hours, a job change, or a move from monthly to irregular income can make an old split unsafe. I would revisit the arrangement whenever the money coming in changes. Keeping an outdated two-part plan can be more dangerous than having no plan because it creates confidence without current support.
The app is also more valuable when paired with a separate emergency reserve. A split schedule is designed for predictable obligations; it does not protect you from repairs, medical costs, or a missed paycheck. If every incoming dollar is assigned to one of the two payment portions, there is no flexibility left. I would use it to organize a recurring bill while keeping at least some room for ordinary surprises.
Compared with a standard banking app, the advantage is focus. A bank can display balances and transactions, but it may not encourage you to think of a major bill as two planned commitments. Compared with a full budgeting app, Split Pay appears more specialized and less mentally demanding for this particular task. The trade-off is breadth: a broader budget tool is better if you need complete category tracking, debt planning, shared household reporting, or detailed spending analysis.
The maintenance that decides everything
No payment-splitting method is truly automatic from a human point of view. You still need to know the due date, protect the reserved money, and make sure the final payment is completed correctly. That maintenance may be light for a stable salary and a fixed bill, but it becomes heavier when income fluctuates or several obligations overlap. I would judge the app by whether it makes those checks clearer, not whether it removes them entirely.
The easiest routine is to choose one recurring payment, decide how the two portions relate to your paydays, and keep the same process for several cycles. Avoid starting with rent, a car payment, utilities, and subscriptions all at once. A single test obligation shows whether you remember the schedule and whether the split fits your actual cash flow. Once that works, adding another major payment is less likely to create confusion.
Timing deserves special attention. Two equal portions may look neat, but equal is not always practical. If one payday falls before several other essential charges and the next comes after the bill is due, an even division may leave you short at the wrong moment. In that situation, an uneven reserve could make more sense, provided the total is still covered. The best split is the one that matches your real income calendar, not the one that looks most symmetrical.
This is also where users should distinguish between a payment plan and a payment method. The app can support the decision to set money aside in two stages, but you should not assume that the final transaction, transfer, or authorization is handled in the same way as a lender’s own system. Before relying on the routine for a high-stakes obligation, I would perform one cycle with extra attention and keep confirmation of the completed payment.
People sharing expenses need an additional layer of clarity. If two adults each contribute, decide whether each person is responsible for one portion or whether both contribute to both portions. Write down the arrangement, including what happens if one person is paid late. The app can help structure the schedule, but it cannot resolve disagreements about ownership, missed contributions, or who checks that the full bill has been paid.
Version 2.0.3 is the current version, and the app works on Android starting with version 7.0. That makes it accessible to many existing Android users, including people who do not have a recent phone. I would still keep the app updated when updates are available, especially for a finance-related tool, and I would avoid treating any single app as the only record of an important payment.
Where monthly fatigue can appear
The main source of fatigue is repetition without visible progress. Once the routine is established, opening an app to think about the same rent or car payment every cycle can feel like another chore. If your bank already lets you create reliable scheduled transfers and you are disciplined about them, the extra layer may not save enough effort to justify itself. In that case, a calendar reminder and a dedicated savings space could be simpler.
Another friction point is irregular income. A two-part plan assumes that the two contributions can be made with reasonable confidence. Freelancers, seasonal workers, and people whose hours change significantly may find that the schedule creates pressure rather than relief. They may be better served by calculating a percentage of each payment received and building a larger reserve before the bill is due, rather than committing to two fixed moments.
Users with many bills may also experience clutter. The concept is strongest when applied to a small number of large recurring obligations. Extending it to every subscription, utility, and discretionary purchase can turn a simple idea into a complicated network of mini-deadlines. I would keep the app focused on the expenses that genuinely cause cash-flow strain. Smaller items are often easier to handle through ordinary account automation.
There is a behavioral risk as well. Seeing a smaller planned amount can make a large obligation feel harmless, encouraging extra spending elsewhere. This is the opposite of the intended result. The app should make the total easier to prepare for, not make the total easier to forget. I recommend displaying the complete monthly obligation somewhere in your budget, even if the app helps you divide the preparation into two parts.
People who need sophisticated financial analysis may outgrow the app quickly. If your priorities include tracking investment performance, forecasting debt interest, reconciling multiple accounts, or managing a detailed family budget, a specialized budgeting platform will probably be the better center of your financial system. Split Pay makes more sense as a focused tool for recurring payment timing than as an all-purpose money manager.
There is also a personal preference involved. Some users feel calmer when one bill is paid in one deliberate action. For them, dividing the preparation may add mental steps instead of removing them. Others feel more secure when every payday contributes toward the next major expense. Neither approach is universally correct. The app earns its place only if its two-stage structure makes your own money routine easier to understand and follow.
Questions I would settle before relying on it
The first question is whether it can replace your existing bank or creditor payment process. I would answer no: use it as part of your planning routine, while continuing to follow the actual payment instructions for rent, mortgage, or car financing. The second question is whether it lowers the amount owed. It does not change the obligation; its value is in organizing how you prepare for it.
Another question is whether it suits someone paid weekly. It can still be conceptually useful, but two fixed contributions may not be the natural fit. A weekly earner might prefer four smaller reserves or a rolling buffer. The app is most persuasive when its two-part structure matches the user’s income pattern rather than forcing a weekly budget into an artificial schedule.
People also wonder whether it is appropriate for shared finances. It can support a shared arrangement if both people agree on the dates, amounts, and responsibility for checking completion. I would not use it as proof that another person has contributed. Keep a simple shared record, particularly when the payment affects housing or a jointly financed vehicle.
Finally, is the free price enough to make it worth trying? Yes, the low commitment makes experimentation reasonable, especially for someone who repeatedly struggles with one large recurring payment. But free does not mean effortless. Give it a full payment cycle, compare the experience with your previous method, and keep it only if you miss fewer steps or feel more in control. That test is more useful than deciding based on the concept alone.
My long-term verdict
I see Split Pay as a focused habit-building tool rather than a complete financial command center. Its first-week appeal is obvious: major recurring payments become easier to frame around two income moments. Its lasting value is more conditional. It remains worthwhile when the user has predictable income, a recurring large obligation, and a genuine need to reduce the pressure of one payment date.
The app is a good fit for a renter, homeowner, or vehicle owner who wants a straightforward way to prepare gradually. It is also useful for someone who understands budgeting but struggles with timing. The most important tip is to treat each planned portion as unavailable money, confirm that the recipient’s payment rules are satisfied, and review the arrangement whenever income or due dates change.
I would skip it if your income is highly unpredictable, your bank already handles the same process cleanly, or you need detailed tracking across many financial categories. In those cases, a reserve-based method or a broader budgeting app may create less friction. The specialized nature that makes Split Pay approachable is also what limits it for complex financial lives.
For me, the app earns lasting space only when it becomes nearly boring: open it, follow the established schedule, verify the payment, and move on. That is a compliment in personal finance. A tool for recurring bills does not need constant excitement; it needs to prevent avoidable surprises. With that expectation, Split Pay is a sensible free option for organizing rent, mortgage, or car-payment preparation, as long as you remember that better timing is not the same as lower cost.
Developed by Split Pay, it carries an Everyone age rating and was released on December 5, 2023. Those details matter less than the daily test: does dividing the preparation into two parts help you keep the full amount safe? If yes, the app can become a useful monthly checkpoint. If not, your bank’s automation, a dedicated reserve, or a simple calendar may be the cleaner long-term answer.
Frequently Asked Questions
What is Split Pay: Split Bills in Two, and how does it work?
Split Pay: Split Bills in Two is designed to make shared expenses easier to manage by dividing a bill between two people. After entering the total amount, users can calculate each person’s share instead of doing the math manually. It is particularly useful for meals, groceries, trips, subscriptions, or any situation where two people need to settle an expense quickly and clearly.
Can Split Pay handle unequal bill splits?
Yes, the app is useful when two people are not paying exactly the same amount. Depending on the available options in the installed version, you can adjust the split rather than relying only on a 50/50 division. This makes it more practical for restaurant bills, different purchases on one receipt, or situations where one person has already contributed more than the other.
Does Split Pay include tax, tips, or additional charges?
Split Pay can be helpful for calculating a final amount that includes extra costs such as tax or a tip, but users should review the available fields and settings in the current version before relying on it for a specific bill. Entering the correct total and checking the result is important, especially when charges are added separately or when rounding affects the final amount.
Is Split Pay: Split Bills in Two free to download and use?
The app’s download availability, pricing, advertisements, and optional in-app purchases may vary between Android and iOS and can change with future updates. Before installing, check the official store listing for the current price and subscription information. Even when the main calculator is free, some versions may include ads or reserve certain convenience features for a paid upgrade.
Is Split Pay safe for entering financial information?
Split Pay is intended for calculating and organizing shared expenses, not for storing sensitive banking credentials or processing payments directly. You generally only need to enter the bill amount and related figures. Nevertheless, users should review the app-store privacy details and requested permissions before downloading, avoid entering card numbers or passwords, and keep the app updated for the best security and compatibility.


